
Getting turned down for business financing can feel like a hard stop—but it’s usually just a detour.
| As Credibly Founder Ryan Rosett noted, “Creditors have checklists, and if your application didn’t check every box, it doesn’t mean you’re out of options. It means you’ve got an opportunity to tighten your strategy and come back stronger.” |
In this guide, we’ll break down the most common reasons business financing applications get denied—and what you can do to strengthen your next application. We’ll show you how to turn today’s “not yet” into a future “you’re approved.”
Understand why your financing application may have been denied
Getting turned down for funding can be discouraging—but it’s not the end of the road. Before you apply again, it’s worth understanding why your application wasn’t approved in the first place.
Sometimes the reason is vague. You might get a generic notice like “information incomplete” or “financials not aligned with requirements.” That doesn’t tell you much. So don’t guess—ask. Reach out to the lender to understand what triggered the rejection. The more you know, the better you can course-correct for next time.
It could be a paperwork issue, a short business history, or a weak cash flow picture. If you’re in an industry going through a slump, that may play a role too. Other times, your credit—business or personal—might be what’s holding you back.
The good news is most of these issues can be fixed. Tighten up your invoicing process. Reduce unnecessary spending. Pay down what you owe. Even small steps can make a big difference the next time you apply for financing.
Top 5 ways you can improve your financing application for next time
Creditors want proof you can manage credit, keep your cash flowing, and handle your current obligations without falling behind. The more boxes you can check, the better your shot at approval.
Let’s walk through the key moves that can make your next financing application stronger.
1. Review & boost your personal and business credit scores
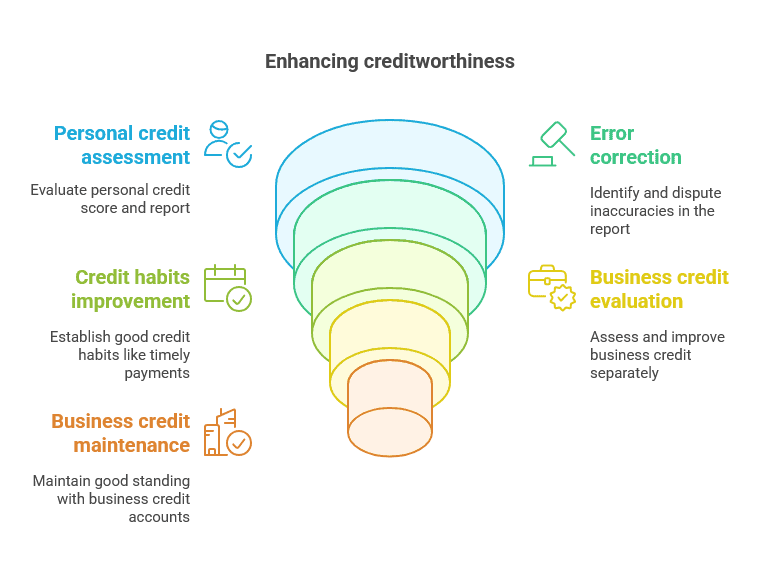
Start by checking your personal credit score. Most creditors want to see strong financial habits. A score in the high 600s or above helps your case, especially with banks and SBA-backed offers. If your score is on the lower side, don’t stress. Many fintech creditors—including Credibly—focus more on revenue and cash flow than perfect credit.
Regardless, it pays to get your score in better shape. Pull your credit report, look for errors, and dispute anything that doesn’t check out. Then build momentum. Pay your bills on time. Use less of your available credit. Keep your balances low. Set up auto-pay so you never miss a due date.
If your business has been around for a while, check your business credit score too. It’s separate from your personal file—and improving it shows creditors you run a stable, reliable operation. Open a business credit account, keep it in good standing, and make sure vendors report your payments.
Credit isn’t the only factor in funding decisions—but it’s one you can control. Start now and give creditors more creditworthiness to say “yes” to next time.
2. Strengthen your cash flow
Creditors want to know you can handle the extra cost of financing—without it tipping your business into the red. If your cash flow’s tight or unpredictable, that’s a red flag. Especially if your bank statements show negative balances or frequent overdrafts.
Before you reapply, get ahead of it. Review your income and expenses to spot leaks. Look at how long it takes to collect on invoices. Tweak your billing process to speed that up if needed. Trim unnecessary costs or renegotiate pricing with your vendors. Even small wins here can begin to create more breathing room.
If cash flow dips are a regular issue, try building in a buffer. Keep a minimum amount in your business account so you’re not scrambling when bills hit. Think about adding a second revenue stream or seasonal service to help smooth out slower months.
The more consistent your cash flow is, the stronger your application is. Show creditors you’ve got a handle on your numbers—and that the financing you’re requesting won’t stretch your business thin.
One “no” isn’t the end of the road for you getting the business financing you needYou’re more than your credit score. We look at where you’re going—not just where you’ve been. Apply online in minutes. |
3. Lower your debt-to-income ratio
Creditors want to see balance—not just in your books, but between what you owe and what you earn. If too much of your income goes toward debt, they may not feel confident adding more to the stack. A high debt-to-income (DTI) ratio can hold your application back, even if the rest of your business looks solid.
Start by paying down the debt you can. If you’re carrying balances on business credit cards or high-interest accounts, focus on paying those down first. This will reduce your monthly debt load and free up cash. You might even score better terms by consolidating what you owe into one lower-cost product.
That said, don’t swing too far the other way. Some creditors like to see active credit usage—not maxed out, but not untouched either. Aim for a utilization rate around 30%. That shows you know how to borrow responsibly and stay in control.
Keep an eye on every account tied to your business. The more intentional you are with your borrowing, the easier it gets to prove you’re a smart bet.
| Discover new ways you could be investing in your business and what you should keep in mind for your business’s financial picture: |
4. Highlight business longevity
How long you’ve been up and running can be the deciding factor for many creditors. It’s one of the first signals they look at when weighing risk. Banks and SBA programs usually want to see at least two years of operations. If your business is still in a startup phase, that alone could be what held your application back.
If timing was the main issue with your application, it might just be a matter of waiting a bit longer before applying again. In the meantime, keep building your revenue, tightening your processes, and tracking your performance. That way, when you reapply, you’re showing not just age—but strength.
If you need capital sooner, consider working with fintech creditors like Credibly. We offer options built for businesses with as little as six months of operating history.
5. Offer collateral
Collateral can be a deal-maker—especially with banks and SBA-backed financing. These creditors often want to see something they can hold as security, whether it’s equipment, vehicles, inventory, or commercial property. Even if they don’t require full coverage of the amount you’re requesting, they’ll usually take whatever assets you’re willing to offer.
If you don’t have hard assets, you’re not out of options. Many creditors will ask for a personal guaranty instead.
Want to improve your odds on your next application? Take stock of what your business owns and what you’re comfortable offering to support your request. Then, match that to creditors who work with businesses like yours—whether that means secured or unsecured financing.
Still feeling stuck after a denial? You’re not alone—and you’re not out of moves. Even if one door closes, there are other paths to secure the funding you need.