Key takeaways
- Myths around business financing cause many owners to stay underfunded and grow slower than they could.
- Many alternative financing providers focus heavily on your cash flow and time in business, not just perfect credit.
- Fast decisions (sometimes in hours) are possible for some files, depending on your business and bank processing times.
- Understanding what providers look for, including revenue consistency, deposits, and Debt Service Coverage Ratio (DSCR), makes you a stronger applicant.
Small business financing feels complicated when you’re surrounded by old advice that no longer fits the way you run your business. Many owners hold back on growth because they’ve heard the same myths repeated for years. The numbers back this up. The 2024 Small Business Credit Survey shows that only 41% of applicants received the full amount they asked for. That gap highlights how the traditional system often works against what SMBs need most: fast financing.
You may feel like you’re running into the same hurdles every time you apply:
- Banks seem selective.
- Credit issues feel like dealbreakers.
- The process drags on with paperwork that slows your next move.
| As Ryan Rosett, CEO of Credibly, puts it: “Misinformation keeps small business owners cautious when they should be capitalizing.” |
In this blog, we cut through the confusion and share the real truth about securing capital quickly. You’ll uncover the myths that keep you underfunded, learn what’s actually true, and discover how to use flexible financing as powerful leverage to scale your operation.
Debunking 5 small business loan myths that keep small business owners underfunded
Small businesses face a constant funding squeeze. Between rising costs, unexpected opportunities, and the push to scale, access to capital can reshape your growth plans. Yet, common misconceptions about securing financing keep many owners on the sidelines.
Thinking of business debt as a last resort can stop you from getting the capital you need to succeed.
- Good debt helps you strengthen your business. It gives you the power to take on new projects, buy equipment, hire staff, or manage busy seasons.
- Bad debt works against you. It drains cash without helping your business produce more.
Strategic financing is more accessible and flexible than most entrepreneurs realize. The key is seeing beyond the myths around small business financing, knowing the truths, and leveraging the right tools to fuel your growth.
Here’s what you need to know.
Myth 1 – Traditional financing providers don’t fund small businesses anymore
Truth: Many banks are stricter, but small business financing providers still fund owners who show consistent revenue, organized records, and a clear plan.
It’s true that the landscape has shifted. Traditional financial institutions often make the process difficult, requiring extensive paperwork and weeks of waiting. Post-pandemic, many established financial providers have raised the approval bar, shifting from an “open-door” approach to a more rigid “prove-your-case” model.
What top financing providers look for now:
- Predictable cash flow.
- Clean, organized business records.
- Business owners who understand their numbers.
The issue is the time it takes to meet these requirements with older systems. Many small business owners need capital faster than those timelines allow.
Credibly helps close that gap. You can get fast and flexible access to capital through a simple online application and direct support from financing experts. When you can show consistent operations and a clear plan, you can be approved in as little as 2 hours and secure funding in as fast as 4 hours. We guide you through the process and help you move forward without the usual slowdown.
Myth 2 – You need perfect credit to get approved
Truth: You don’t need perfect credit to get small business financing. Many online small business financing providers can consider credit scores as low as 500, alongside your revenue, deposits, and time in business.
Perfect credit is certainly helpful, but it’s not a must-have. We believe a FICO score shouldn’t be the only thing that defines your ability to run a successful business. Many traditional institutions reduce you to that single number, but Credibly sees the bigger picture.
We understand that owners come from all walks of life, and shouldn’t be reduced to their P&L sheets or a credit score. Credibly focuses on overall business health over FICO alone, including revenue trends, average monthly deposits and how you manage cash, not just a single score.
Even with a dented credit history (we typically consider minimum FICO scores as low as 500 for our core products), you are not automatically disqualified.
When the bank says no, we say, “Tell us about your business.” We look for steady operations and consistency. You only need a small amount of documentation to get started, which keeps the application simple.
Typical eligibility ranges for Credibly products:
- Average monthly deposits: $20K+
- Time in business: 6+ months
- Personal credit: FICO 500+
- Other factors: Revenue consistency, operational stability, ability to handle existing obligations
The truth is, strong financial habits and clear growth trends carry more weight than past issues. When you show discipline in how you manage your money, approval becomes about whether the financing fits your next step.
| Learn more about financing opportunities: |
Myth 3 – Securing capital is always complicated and costly
Truth: Flexible financing is not the risk. Confusion is. When financing providers rush decisions, business owners pay for it later.
Many business owners think that flexible financing always comes with confusing terms or high costs. That belief often comes from past experiences with providers who weren’t clear or upfront. It makes the whole process feel risky before you even start.
According to the U.S Chamber of Commerce, big banks said “yes” to barely 13% of small business applicants in November 2023. Meanwhile, alternative lenders opened their doors to 30%. Modern fintech platforms have changed how owners access capital, giving you a faster, clearer, and more transparent path forward.
Here’s why small businesses choose Credibly as their online small business financing provider:
- Speed and flexibility: We can approve applications in as fast as 2 hours, with funding available in as fast as 4 hours, aiming to serve deserving business owners who are overlooked by traditional banks.
- Focus on potential: We fund based on your business performance and revenue consistency, not just perfect credit scores. Upon approval, we can provide capital when and where you need it most.
- Supportive structure and terms: We are invested in helping our community grow and adapt. We structure flexible rates and terms to align with your cash flow and business needs, and we explain total costs up front.
The real risk isn’t the provider. It’s moving ahead without understanding what you’re agreeing to. That’s why Credibly commits to being transparent and a trusted expert. We make sure you understand everything clearly before you sign, including the total remittance amount.
A good financing partnership is one where the provider offers a clear guideline for what to look out for:
- Clarity on cost: Is the cost structure (factor rate) fully explained and simple to understand?
- Ease of application: Can you complete the entire application easily online and digitally?
- Human support: Do you have access to a live, US-based financing expert for advice and support?
Myth 4 – Grants are easy money
Truth: Grants are not quick capital. They are slow, competitive, and highly restrictive. While they can support specific programs, they rarely solve immediate business needs.
The idea of “free money” might sound great, but grants rarely work that way. Most grants support specific industries or goals, not everyday business needs. They come with heavy competition, strict timelines, and detailed requirements like proposals, financial records, and proof of your impact.
Federal, state, and local grants are out there, but they take time and careful planning. Many business owners end up spending weeks chasing grant opportunities that don’t move their business forward. No agency can promise approval, and the process often stretches out over months.
Myth 5 – Using financing means your business is failing
Truth: Debt is not a sign of failure. It is a growth tool when used with intent. Businesses that rely only on organic cash flow often grow slower and miss opportunities. Strategic financing gives owners the ability to invest, measure return, and move quickly, turning planned action into measurable profit.
Debt does not signal trouble; it signals leverage and strategic intent when you choose the right financing structure for your business. Every successful, growing company, from ambitious small businesses to market leaders, utilizes financing to expand, innovate, and proactively adapt to market shifts.
Avoiding all outside capital can limit how quickly you can grow. The goal is to use borrowed funds smartly to achieve goals faster than organic growth alone. At Credibly, we understand that your ideas and business goals have the potential to create new opportunities and promote growth.
Smart business owners use financing to transform potential into profit. Instead of treating small business financing as a last resort, they treat it as a planning tool. They:
- Measure ROI: They track the return on investment for every financed initiative, ensuring the capital is a tool for scaling.
- Invest proactively: They use funds to acquire new equipment, add key team members, or expand market reach, giving them a competitive edge.
- Maintain flexibility: They choose flexible financing options that allow them to adapt quickly when traditional systems bog them down with red tape.
When you partner with a trusted small business financing provider, you gain the ability to act decisively with access to the capital you need quickly. Leverage today’s opportunities to secure tomorrow’s success.
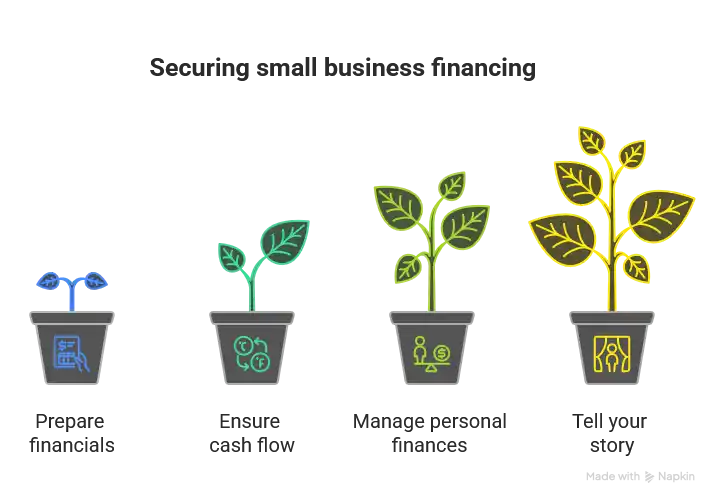
4 key factors small business financing providers look at (a Credibly case study)
Financing providers typically consider (1) your preparation and financial records, (2) cash flow trends, (3) personal finances, (4) your overall debt capacity (DSCR) and (5) your business story and growth plan.
Every small business financing approval decision ultimately boils down to one simple question: Can your business generate enough consistent revenue to comfortably handle the remittances?
Here’s what actually drives funding decisions:
1. Preparation beats guesswork
Financing providers don’t fund ideas; they fund signs that your business is steady and ready to grow. We want to see that you have a plan, you understand your operation, and you’re building something sustainable. That’s why our digital application keeps things simple and asks for far less paperwork than you might expect.
You should be ready to demonstrate:
- Financial health: A simple look at your assets and liabilities.
- Profitability: Proof that you turn revenue into real gains.
- Cash flow statements: The most important piece. Consistent cash coming in and out shows your ability to handle remittances.
A strong understanding of your business plan and its numbers shows a financing provider how the capital will grow your operation, not just how much money you want.
2. Cash flow rules everything
Revenue looks good on paper, but consistent cash flow is what remits the capital. That’s why Credibly digs deep into how money moves through your business. It’s a crucial part of evaluating your future potential. Strong profits with unstable cash flow still raise red flags for any provider.
When reviewing applications, we look for patterns that demonstrate reliability:
- Are your inflows predictable and recurring (e.g., $20K+ avg. monthly deposits)?
- Are your outflows stable and managed?
- Can your cash cycle absorb the daily or weekly remittances without strain?
Even with average credit, steady cash flow proves the operational health that we value. The control you show over your cash is the best collateral you can offer. Systems that track spending, manage invoices, and forecast revenue make your application stronger than any motivational pitch.
3. Personal finances still count (But not everything)
Your personal finances still matter, especially for younger companies, when you’re applying for small business financing. Many financing providers view you and your business as a single unit. It’s how they get that “global picture” of financial discipline. Financing providers want to see a history of strong payment behavior.
This includes reviewing elements like your:
Credit history
We look at your FICO score and payment behavior. While some aim for a score above 700, remember that Credibly can consider applications with FICO scores as low as 500 for our core products. Strong business performance and consistent revenue can absolutely offset a lower personal score.
Financial Safety Net
A look at your personal assets and liabilities gives us a sense of your overall financial management. If you manage your personal finances well, a trusted financing provider will trust you to handle business financing obligations responsibly.
4. There are no hard rules
There’s no single secret formula that guarantees approval. Different businesses have different financial shapes, and smart financing providers know this. The decision is based on your unique situation.
For instance, consider the Debt Service Coverage Ratio (DSCR):
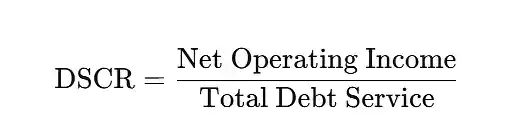
A common benchmark is a DSCR above 1.25, which means your business earns $1.25 for every $1 in debt payments. But this number isn’t absolute.
A manufacturer with substantial assets can carry more debt, while a service-based business could carry less. Strong, recurring contracts or consistent monthly deposits can often offset a weaker DSCR.
We look at the total picture, balancing multiple factors to see your business’s true potential:
- Income consistency (e.g., $20K+ avg. monthly deposits).
- Market trends.
- Your equity position (how much of your own stake you’ve built into the company).
Don’t let small business financing myths hold your business backDiscover fast, reliable small business financing and take control of your next move. |
How to choose the right small business financing partner
Choosing a financing provider is about more than finding the lowest rate. As you compare your options, ask questions like:
- Funding speed:
- How quickly does this provider typically review and fund small business financing applications?
- Can they sometimes approve applications in as fast as 2 hours, with funding available in as fast as 4 hours?
- Remittance structure:
- Do the remittance terms match the way your business runs?
- Do daily or weekly remittances support your cash-flow cycle instead of creating stress?
- Transparency:
- Does the provider clearly show your total remittance amount, factor rate, and all fees upfront?
- Are there any surprises or hidden costs buried in the agreement?
- Customer support:
- Will getting capital feel personal, not transactional?
- Do you have access to a live, US-based financing expert for advice and support before and after funding?
- Flexibility:
- Does the provider support renewals or increased limits as you grow?
- Are they focused on building an ongoing relationship, not just a one-time transaction?
The truth about small business financing (Why it’s not the enemy)
Financing doesn’t hold you back; hesitation does. The most successful business owners treat capital as a lever. Used strategically, it multiplies results and helps you unlock the next stage of growth.
Most of the confusion around small business financing fades once you understand how trusted financing providers think. They don’t expect perfection; they expect preparation and potential.
With the right partner, securing capital becomes an ally in:
- Scaling operations and expanding your market reach.
- Hiring key talent when you need it most.
- Surviving slow months with financial stability.
Stop believing the myths. Start leveraging the truth.
Small business financing FAQs
Do I need perfect credit to get small business financing?
No, you don’t need perfect credit to access small business financing. Many online small business financing providers can consider credit scores as low as 500, as long as your business shows consistent revenue, steady deposits and time in business.
At Credibly, your FICO score is just one factor among several, alongside your cash flow, average monthly deposits and overall business performance.
How fast can small business financing providers fund my business?
Some small business financing providers can approve applications in as fast as 2 hours, with funding available in as fast as 4 hours, depending on your file and bank processing times.
Speed usually comes down to having organized records, consistent deposits and a clear plan for how you’ll use the capital. While there are no guarantees, strong preparation often makes the process much faster and smoother.
What revenue do I typically need to qualify with Credibly?
For many of Credibly’s core products, providers typically look for $20k+ in average monthly deposits and at least 6+ months in business. Consistent revenue, predictable cash flow and a manageable history of existing obligations all help strengthen your application.
Exact requirements can vary by product and file, but healthy, recurring deposits are one of the most important signals.
What’s the difference between a working capital loan and a merchant cash advance?
A working capital loan*** is a small business financing option with a set term and structured remittances, often used for inventory, equipment and general growth needs.
A merchant cash advance (MCA)*** is not a loan; it’s a purchase of a portion of your future receivables, typically used for quick cash flow needs and seasonal gaps, with daily or weekly remittances designed to align with your cash-flow cycle.
Both can be useful tools, but they fit different business needs and risk tolerances, so it’s important to compare structures, total remittance amounts and how each option interacts with your cash flow.
Comparing Credibly’s small business financing options
Use this quick-reference guide to benchmark the financing choices available through Credibly and our network of partners.
| Financing Option | Typical Use Case |
| Working capital loan*** | Inventory, equipment, general growth needs |
| Merchant cash advance*** | Quick cash flow needs, seasonal gaps |
| Small business line of credit** | Short-term cash flow buffer, emergency funds |
| Long-term business loan** | Major expansion, real estate, large capital expenditures |
| SBA loan** | Long-term, low-cost financing for growth |
Ready to turn your vision into capital?
It’s time to skip the friction and secure the funds your business deserves.
| Important compliance notes
*Factor rates are included in your daily estimate to simplify remittances and account monitoring. Factor rates as low as 1.11. **Some products are made available through Credibly’s network of external funding partners. ***Credibly merchant cash advances and working capital loans to merchants in California are provided by Retail Capital LLC. All other Credibly products in all other jurisdictions are provided by Credibly or Arizona LLC. Financing terms are based on a good-faith estimate and assume consistent monthly revenue. Actual time to satisfy the MCA may vary. |